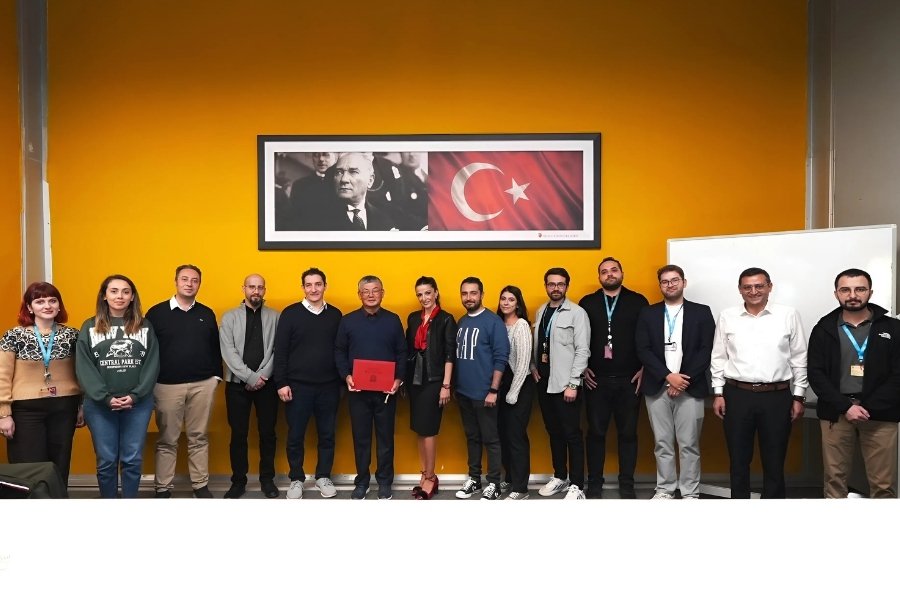
Seminar on Advanced Techniques in Economic Data Analysis Completed
Prof. Dr. Junsoo Lee presented new approaches to IV unit root tests in econometrics, discussing estimation methods, trend analysis, and model development.
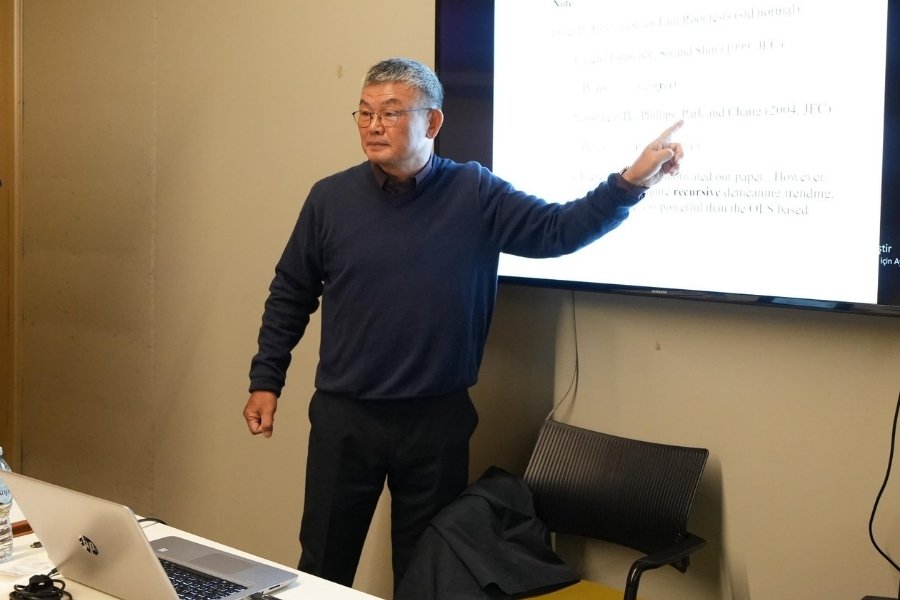
A seminar at İstanbul Nişantaşı University NeoTech Campus featured Prof. Dr. Junsoo Lee from the University of Alabama’s Economics Department, who presented new approaches to “Stable IV Unit Root Tests.” The seminar highlighted the wide application of instrumental variable (IV) estimation in econometric analysis. Beginning with Brownian processes, Lee discussed its applications and current debates. He also addressed test statistics arising when IV estimates are stable and explained when standard normal results apply. With audience contributions, participants discussed detrending methods, trend shifts and the DF Trend Method, offering suggestions for their improvement.
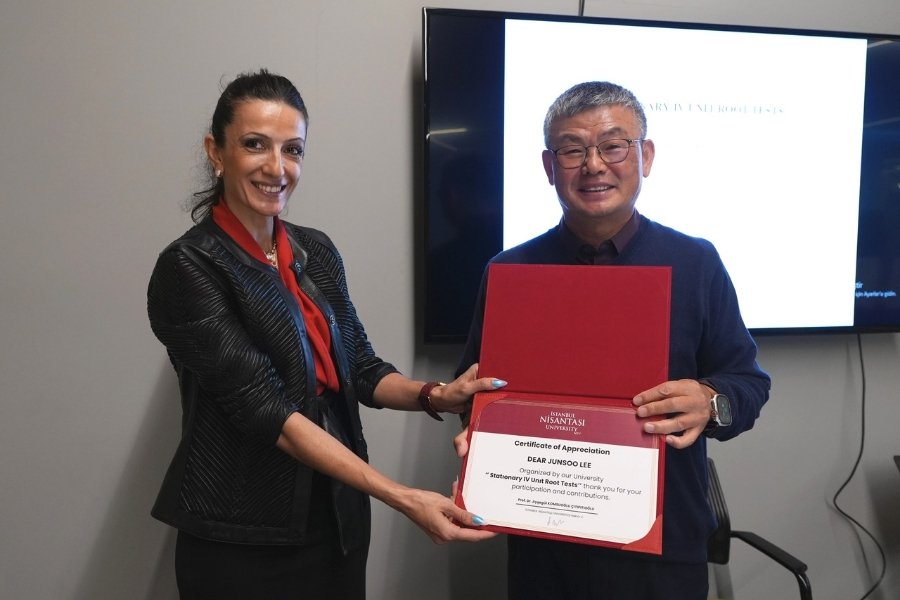
Prof. Dr. Lee went on to explain how different model structures could become more flexible and effective, providing details on weighted moments and RALS procedures. Pointing out shortcomings in IV estimation, he emphasised the need for further development. He proposed model averaging estimators, Fourier functions and extensions to cointegration tests, noting that research remains ongoing. The seminar concluded with a participation certificate presented to Prof. Junsoo Lee.